- Home
- Who we serve
- Public Schools
Public Schools
Audit and accounting support shaped around capitation, Board of Management oversight and the public-sector reporting calendar.
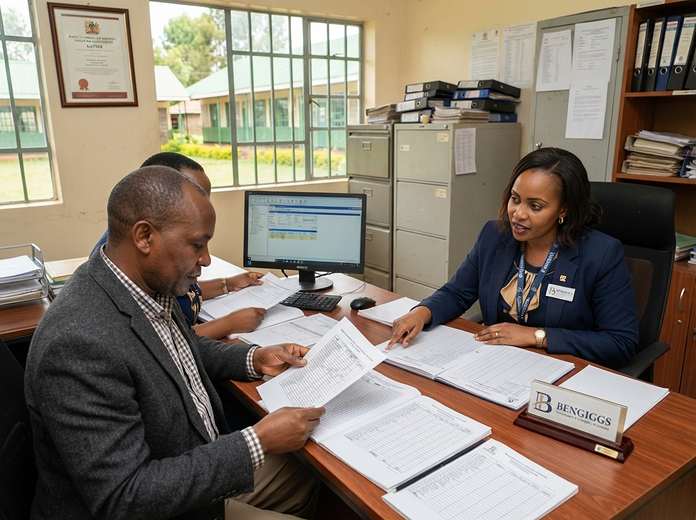
Public schools account for public money. Every shilling of capitation must be receipted, tracked and reported — under IPSAS, on a financial year ending 30 June, under the oversight of the Board of Management and the County Education Board, and subject to audit by the Office of the Auditor-General. We work inside this framework every day.
The challenges we solve
Capitation & grant accountability
Ring-fenced funds must be tracked, receipted and reported term by term, vote by vote — with files that stand up to inspection.
IPSAS cash-basis reporting
Statements of receipts and payments, assets and liabilities, and cash flows that are complete, accurate and on time.
Procurement & stores discipline
Procurement records and stores controls that survive audit queries — quotations, minutes, delivery and issue records.
BOM-employed staff payroll
Payroll for BOM-employed teachers and support staff with PAYE, NSSF, SHIF and Housing Levy handled correctly every month.
Audit queries & OAG liaison
Preparing complete audit files and responding to findings without disrupting the school calendar.
How we typically support public schools:
- Internal audit and controls reviews between statutory audits
- Bookkeeping support and IPSAS-aligned financial statements
- Payroll bureau for BOM-employed staff
- Procurement and stores systems advisory
- Audit-readiness training for bursars and finance committees